Asian Family-Style Restaurants insurance · Nationwide
Insurance that understands a wok kitchen
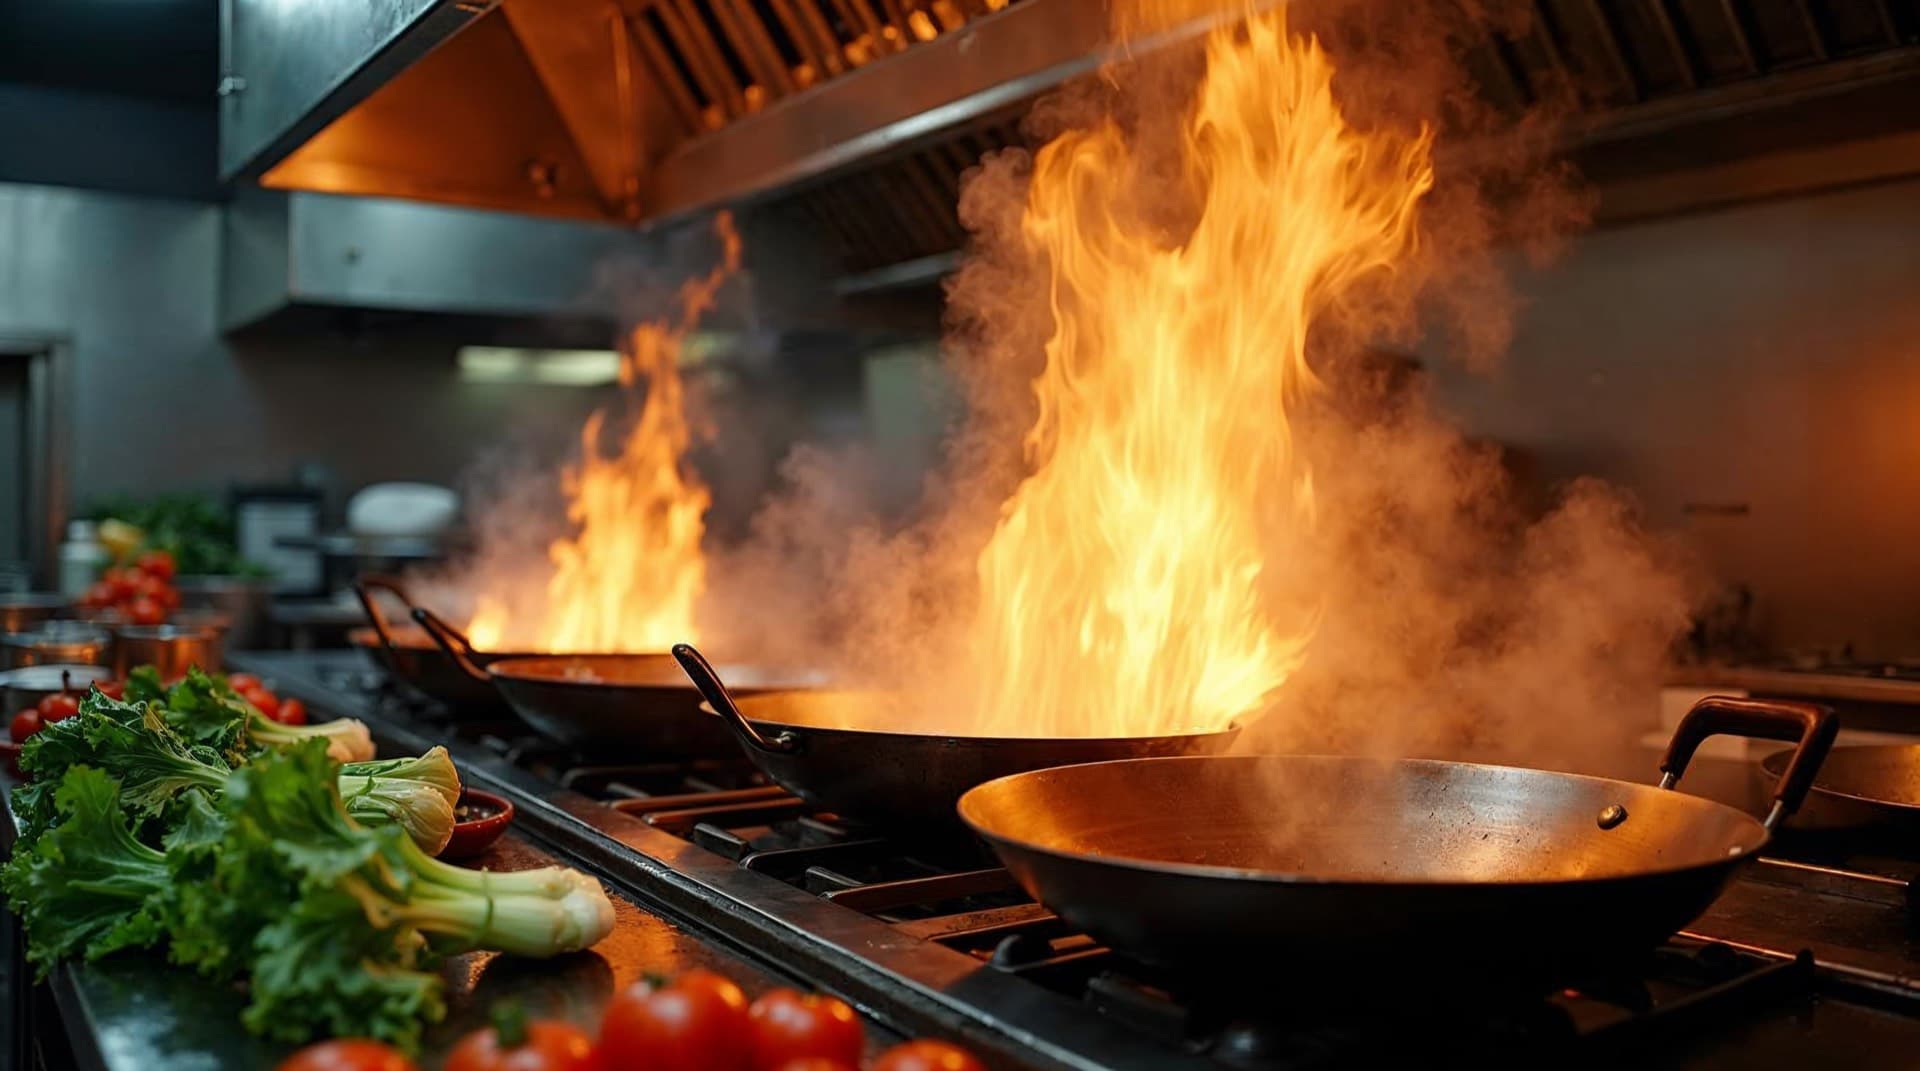
High-BTU wok burners, flash-point oils, and a kitchen that runs hotter than a standard range. Asian restaurant kitchens carry fire and equipment risk that a generic restaurant policy can underestimate. We connect you with specialists who ask the right questions.
Ready now
Start your quote
One short page. A licensed Asian restaurant specialist compares A-rated carriers and calls you back.
Still figuring it out
See what your work requires
Use our Compass to learn exactly what your specific use case might require.
Open the Compass →Where Asian restaurants get exposed
These are the scenarios our specialists see most often in your industry.
Hover a moment in the day to see the risk
Coverage Asian restaurants carry
High-heat cooking is what sets this kitchen apart from a general restaurant. Wok ranges, deep fryers and tandoors run hotter and produce more grease-laden vapor than a standard line, which changes both the fire risk and what a carrier will ask you about.
Business Owner's Policy (BOP)
Liability and property in a single package, underwritten around your hood, duct, and suppression system.
The usual starting point. Expect the property side to be underwritten around your hood, duct and suppression system rather than the size of the dining room.
General Liability
Guest injuries in the dining room, plus allergen and foodborne-illness claims arising from what you serve.
Allergen exposure deserves particular attention here: shellfish, peanut and sesame are common across the menu, and a reaction is a product-liability claim.
Workers' Compensation
Medical bills and lost wages for burns, oil splash, cuts, and slips on a high-heat line.
Wok and fryer stations produce more severe burns than a standard kitchen. Required in nearly every state once anyone is on payroll.
Commercial Property
Wok ranges, fryers, hoods, furnishings, and inventory against fire and water damage.
Grease build-up in ductwork is the single biggest driver of a total loss in this format. Your cleaning schedule is effectively part of the underwriting.
Commercial Auto
Delivery vehicles and drivers: liability, collision, and hired or non-owned autos.
Delivery is a larger share of revenue here than in most formats. Drivers in their own cars need hired and non-owned, which is where this is usually missed.
FAQFrequently Asked Questions
It should. Wok stations run hotter than a standard range, and insurers who don't ask about your actual equipment can undervalue your hood, suppression system, and fire exposure. We connect you with specialists who ask.
That's a fire-code and insurer evaluation question specific to your kitchen: high-BTU wok burners often need a higher-capacity hood and suppression system than a standard range setup. We'll help you get that properly assessed.
Commercial property coverage extends to the full covered loss, including smoke and fire damage that spreads beyond the immediate cooking area, plus business interruption coverage for lost income while you rebuild.
The core coverage, general liability for foodborne illness claims, is the same, but volume and cross-contamination risk from high-throughput raw prep is worth discussing directly with your specialist when setting limits.